What to Check Before Choosing a Crypto Card

Imagine you’ve just set up a wallet and the next logical step feels like grabbing a plastic gateway to spend your digital assets. The excitement fades fast when you stare at the maze of card options, hidden fees, and jurisdictional quirks that could turn a smooth transaction into a painful chase. This is why a solid checklist isn’t a luxury—it’s the only way to protect your crypto and keep your finances on‑track.

Meanwhile, the market throws buzzwords at you like “instant” and “zero‑fee” while the fine print whispers about conversion spreads and network throttling. Skipping the vetting process is like stepping onto a moving train with no seat belt; you might enjoy the ride, but a sudden jolt could leave you bruised. Let’s cut through the hype and focus on the concrete factors that truly matter.

Security Foundations and Custodial Models

When you hand over a card, you’re effectively delegating custody of your crypto to a third party, and that delegation demands ironclad security. Look for multi‑factor authentication, hardware‑secure elements, and a clear policy on how private keys are stored. A card that keeps keys on‑device, isolated from the internet, reduces exposure dramatically compared to custodial solutions that sit behind a single cloud API.

First, scrutinize the encryption standards; a reputable provider will tout AES‑256 or similar, but beware of vague claims like “bank‑grade security” without technical backing. If the provider references a known security audit, chase the report and verify its findings—transparency here is non‑negotiable. You can read more on the topic at cryptocardbasics.com, where the nuances of key management are broken down in plain English.

Consider the insurance coverage offered for loss or theft. Some cards bundle a modest indemnity that kicks in only after a lengthy claim process, while others partner with established insurers for a more reliable safety net. A token‑based insurance model may look attractive, but the fine print often caps payouts at levels far below typical crypto balances.

Security isn’t just about tech—it’s about the company’s track record. Check if they’ve been subject to any major breaches or regulatory penalties. A clean history doesn’t guarantee future safety, but it does signal a commitment to maintaining robust defenses and responding swiftly to emerging threats.

Liquidity matters too; a card that can instantly convert crypto to fiat at low spreads is essential for real‑world use. If the card relies on a sluggish internal exchange, you may find yourself stuck with a token that can’t pay for a coffee in a timely manner, turning convenience into frustration.

Fees and Hidden Costs

Understanding fee structures is akin to reading the fine print on a loan agreement—you’ll spot the hidden costs before they bite. Many cards advertise “zero transaction fees,” yet they compensate through higher exchange spreads or inactivity charges that silently drain your balance over time.

Typical fee categories include issuance costs, ATM withdrawal surcharges, and cross‑border conversion penalties. Some providers waive the issuance fee if you meet a minimum spend, while others embed a tiny percentage into every transaction. Evaluate which model aligns with your spending habits, and remember that a small upfront fee may be worth it if it eliminates recurring micro‑charges.

Exchange Rates and Conversion

Exchange rates often hide the most volatile component of a crypto card’s cost structure. Providers may quote a “mid‑market” rate but add a markup that widens the spread, especially during high volatility. Look for cards that disclose their exact spread or that use reputable on‑chain aggregators to fetch rates in real time.

Transparency in rate calculation builds trust. If a card publishes a live feed of its conversion rates, you can compare it directly against market sources. Some firms even let you lock in a rate for a short window, shielding you from sudden swings during travel or large purchases.

User‑experience suffers when fees are unpredictable. Sudden surcharges can make a seemingly cheap purchase feel like a ripoff, and that shock factor often discourages further usage. Choose a card that offers a clear, flat‑fee schedule, or at least caps unexpected costs to a modest, well‑communicated ceiling.

Card Compatibility and Acceptance

Retail acceptance varies dramatically across regions, and a card that shines in one country may flounder in another. Verify whether the card works on major networks like Visa or Mastercard, because those logos guarantee the widest merchant coverage and easier integration with existing point‑of‑sale systems.

Travel scenarios amplify acceptance concerns; border controls and currency exchanges can trip up cards that lack universal network support. If you frequently cross borders, prioritize a card that offers seamless multi‑currency handling and partners with global ATM networks to avoid dreaded “card not supported” messages.

Online merchants often require tokenised card numbers to comply with PCI standards, and some crypto cards fail to generate the necessary tokens. Before committing, test the card on a handful of popular e‑commerce platforms to see if the checkout process runs smoothly without extra verification hoops.

Emerging markets present both opportunity and risk. While crypto adoption may be higher, the underlying banking infrastructure can be less stable, leading to occasional outages or delayed settlements. Look for providers that have built redundancy into their processing pipelines, ensuring your transaction isn’t caught in a local network glitch.

Regulations shape acceptance as much as technology. Some jurisdictions ban the use of crypto‑linked cards altogether, or impose stricter KYC requirements that can halt services abruptly. Checking a card’s compliance stance against your home country’s rules prevents unpleasant surprises down the line.

Rewards, Cashback, and Perks

Earned rewards can sweeten the deal, but they often come with strings attached that negate their value. Some cards tout “crypto‑back” on purchases, yet they impose a minimum spend threshold before any rewards unlock, turning an attractive feature into a long‑term grind.

Staking incentives are another lure; a card may offer higher rewards if you lock up a portion of your holdings. While staking can boost returns, it also reduces liquidity and exposes you to market risk—if the token’s price dips, you’re locked into a lower‑value asset while still needing to spend.

Cashback percentages differ between categories—travel, dining, and groceries each have distinct reward rates. If your spending profile leans heavily toward one category, pick a card that maximizes returns there, rather than a jack‑of‑all‑trades with mediocre payouts across the board.

Tiered reward structures reward frequent users with boosted rates, but they often require a monthly spend that eclipses casual usage. Evaluate whether you can realistically hit those tiers; otherwise, you’ll end up paying higher fees for the illusion of premium benefits.

Limits on rewards and cashback caps are common, and they can silently truncate your earnings once you hit a modest ceiling. Choose a card whose reward ceiling aligns with your typical monthly expenditure, or opt for a flat‑rate system that offers consistent returns without an arbitrary stop‑line.

Customer Support and Reputation

Responsive support can be the difference between a quick resolution and a prolonged headache when your card glitches. Look for providers that offer 24/7 live chat or phone lines staffed by knowledgeable agents familiar with both crypto nuances and traditional banking protocols.

Community feedback often reveals hidden pitfalls; browse forums, Reddit threads, and social media groups to gauge real‑world experiences. A card boasting glossy marketing material may have an undercurrent of unresolved complaints that only active users discuss openly.

Reviews highlight recurring pain points such as delayed cash withdrawals, unclear fee reversals, or inconsistent KYC processes. Prioritize cards with a track record of addressing these concerns promptly, and note whether the company publicly shares its roadmap for improving service quality.

Service quality can vary wildly across regions, especially if a provider outsources support to third‑party call centers. Confirm that the support language, time zones, and escalation procedures match your expectations, so you’re not left waiting for a resolution that spans continents.

Take the final step: sign up for a test card, run a small transaction, and gauge the entire ecosystem—from onboarding speed to the clarity of your transaction receipt. That hands‑on trial will tell you instantly whether the card lives up to the checklist or merely masquerades as a premium product.

Related posts

What to Check Before Choosing a Crypto Card

Imagine you’ve just set up a wallet and the next logical step feels like grabbing a plastic gateway to spend your digital assets. The excitement fades fast when you stare at the maze of card options, hidden fees, and jurisdictional quirks that could turn a smooth transaction into a painful chase. This is why a solid checklist isn’t a luxury—it’s the only way to protect your crypto and keep your finances on‑track.

Meanwhile, the market throws buzzwords at you like “instant” and “zero‑fee” while the fine print whispers about conversion spreads and network throttling. Skipping the vetting process is like stepping onto a moving train with no seat belt; you might enjoy the ride, but a sudden jolt could leave you bruised. Let’s cut through the hype and focus on the concrete factors that truly matter.

Security Foundations and Custodial Models

When you hand over a card, you’re effectively delegating custody of your crypto to a third party, and that delegation demands ironclad security. Look for multi‑factor authentication, hardware‑secure elements, and a clear policy on how private keys are stored. A card that keeps keys on‑device, isolated from the internet, reduces exposure dramatically compared to custodial solutions that sit behind a single cloud API.

First, scrutinize the encryption standards; a reputable provider will tout AES‑256 or similar, but beware of vague claims like “bank‑grade security” without technical backing. If the provider references a known security audit, chase the report and verify its findings—transparency here is non‑negotiable. You can read more on the topic at cryptocardbasics.com, where the nuances of key management are broken down in plain English.

Consider the insurance coverage offered for loss or theft. Some cards bundle a modest indemnity that kicks in only after a lengthy claim process, while others partner with established insurers for a more reliable safety net. A token‑based insurance model may look attractive, but the fine print often caps payouts at levels far below typical crypto balances.

Security isn’t just about tech—it’s about the company’s track record. Check if they’ve been subject to any major breaches or regulatory penalties. A clean history doesn’t guarantee future safety, but it does signal a commitment to maintaining robust defenses and responding swiftly to emerging threats.

Liquidity matters too; a card that can instantly convert crypto to fiat at low spreads is essential for real‑world use. If the card relies on a sluggish internal exchange, you may find yourself stuck with a token that can’t pay for a coffee in a timely manner, turning convenience into frustration.

Fees and Hidden Costs

Understanding fee structures is akin to reading the fine print on a loan agreement—you’ll spot the hidden costs before they bite. Many cards advertise “zero transaction fees,” yet they compensate through higher exchange spreads or inactivity charges that silently drain your balance over time.

Typical fee categories include issuance costs, ATM withdrawal surcharges, and cross‑border conversion penalties. Some providers waive the issuance fee if you meet a minimum spend, while others embed a tiny percentage into every transaction. Evaluate which model aligns with your spending habits, and remember that a small upfront fee may be worth it if it eliminates recurring micro‑charges.

Exchange Rates and Conversion

Exchange rates often hide the most volatile component of a crypto card’s cost structure. Providers may quote a “mid‑market” rate but add a markup that widens the spread, especially during high volatility. Look for cards that disclose their exact spread or that use reputable on‑chain aggregators to fetch rates in real time.

Transparency in rate calculation builds trust. If a card publishes a live feed of its conversion rates, you can compare it directly against market sources. Some firms even let you lock in a rate for a short window, shielding you from sudden swings during travel or large purchases.

User‑experience suffers when fees are unpredictable. Sudden surcharges can make a seemingly cheap purchase feel like a ripoff, and that shock factor often discourages further usage. Choose a card that offers a clear, flat‑fee schedule, or at least caps unexpected costs to a modest, well‑communicated ceiling.

Card Compatibility and Acceptance

Retail acceptance varies dramatically across regions, and a card that shines in one country may flounder in another. Verify whether the card works on major networks like Visa or Mastercard, because those logos guarantee the widest merchant coverage and easier integration with existing point‑of‑sale systems.

Travel scenarios amplify acceptance concerns; border controls and currency exchanges can trip up cards that lack universal network support. If you frequently cross borders, prioritize a card that offers seamless multi‑currency handling and partners with global ATM networks to avoid dreaded “card not supported” messages.

Online merchants often require tokenised card numbers to comply with PCI standards, and some crypto cards fail to generate the necessary tokens. Before committing, test the card on a handful of popular e‑commerce platforms to see if the checkout process runs smoothly without extra verification hoops.

Emerging markets present both opportunity and risk. While crypto adoption may be higher, the underlying banking infrastructure can be less stable, leading to occasional outages or delayed settlements. Look for providers that have built redundancy into their processing pipelines, ensuring your transaction isn’t caught in a local network glitch.

Regulations shape acceptance as much as technology. Some jurisdictions ban the use of crypto‑linked cards altogether, or impose stricter KYC requirements that can halt services abruptly. Checking a card’s compliance stance against your home country’s rules prevents unpleasant surprises down the line.

Rewards, Cashback, and Perks

Earned rewards can sweeten the deal, but they often come with strings attached that negate their value. Some cards tout “crypto‑back” on purchases, yet they impose a minimum spend threshold before any rewards unlock, turning an attractive feature into a long‑term grind.

Staking incentives are another lure; a card may offer higher rewards if you lock up a portion of your holdings. While staking can boost returns, it also reduces liquidity and exposes you to market risk—if the token’s price dips, you’re locked into a lower‑value asset while still needing to spend.

Cashback percentages differ between categories—travel, dining, and groceries each have distinct reward rates. If your spending profile leans heavily toward one category, pick a card that maximizes returns there, rather than a jack‑of‑all‑trades with mediocre payouts across the board.

Tiered reward structures reward frequent users with boosted rates, but they often require a monthly spend that eclipses casual usage. Evaluate whether you can realistically hit those tiers; otherwise, you’ll end up paying higher fees for the illusion of premium benefits.

Limits on rewards and cashback caps are common, and they can silently truncate your earnings once you hit a modest ceiling. Choose a card whose reward ceiling aligns with your typical monthly expenditure, or opt for a flat‑rate system that offers consistent returns without an arbitrary stop‑line.

Customer Support and Reputation

Responsive support can be the difference between a quick resolution and a prolonged headache when your card glitches. Look for providers that offer 24/7 live chat or phone lines staffed by knowledgeable agents familiar with both crypto nuances and traditional banking protocols.

Community feedback often reveals hidden pitfalls; browse forums, Reddit threads, and social media groups to gauge real‑world experiences. A card boasting glossy marketing material may have an undercurrent of unresolved complaints that only active users discuss openly.

Reviews highlight recurring pain points such as delayed cash withdrawals, unclear fee reversals, or inconsistent KYC processes. Prioritize cards with a track record of addressing these concerns promptly, and note whether the company publicly shares its roadmap for improving service quality.

Service quality can vary wildly across regions, especially if a provider outsources support to third‑party call centers. Confirm that the support language, time zones, and escalation procedures match your expectations, so you’re not left waiting for a resolution that spans continents.

Take the final step: sign up for a test card, run a small transaction, and gauge the entire ecosystem—from onboarding speed to the clarity of your transaction receipt. That hands‑on trial will tell you instantly whether the card lives up to the checklist or merely masquerades as a premium product.
Related posts

CLOSE

Cookies Policy

Effective Date: 03/07/2023

This Cookies Policy (“Policy”) explains how Oculina.co.uk (“we,” “us,” or “our”) uses cookies and similar technologies when you visit our website, located at www.oculina.co.uk (“Website”). This Policy also outlines your choices regarding the use of cookies.

What are cookies?

Cookies are small text files that are placed on your device (such as a computer, smartphone, or tablet) when you visit a website. They are widely used to make websites work more efficiently, enhance user experience, and provide useful information to website owners.

How do we use cookies?

We use cookies for the following purposes:

  1. Essential cookies: These cookies are necessary for the functioning of our Website and enable you to navigate and use its features. Without these cookies, certain services may not be provided.
  2. Analytics cookies: We use analytics cookies to collect information about how visitors use our Website. This helps us analyze and improve the performance and functionality of our Website. The information collected through these cookies is aggregated and anonymous.
  3. Preference cookies: These cookies allow our Website to remember your preferences and choices (such as language or region) to provide a personalized experience.
  4. Marketing cookies: We may use marketing cookies to track your browsing activities across different websites. This allows us to deliver relevant advertisements and promotional materials that may be of interest to you.

Third-party cookies

We may allow third-party service providers, such as analytics and advertising partners, to place cookies on your device when you visit our Website. These third parties may use cookies to collect information about your online activities over time and across different websites.

Cookie management

By default, most web browsers are set to accept cookies automatically. However, you can manage and control cookies in various ways. You can typically configure your browser settings to block cookies, delete existing cookies, or prompt you before accepting cookies. Please note that if you choose to disable cookies, certain features of our Website may not function properly, and your browsing experience may be affected.

To learn more about managing cookies, you can refer to the “Help” or “Settings” section of your browser or visit the websites of your browser’s developer.

Your consent

By continuing to use our Website, you consent to the placement of cookies on your device as described in this Policy. If you do not agree to the use of cookies, you should discontinue using our Website.

Updates to this Policy

We may update this Policy from time to time to reflect changes in our use of cookies or applicable regulations. Any updates to this Policy will be posted on our Website, and the revised version will indicate the “Effective Date” at the top. We encourage you to review this Policy periodically for any changes.

Contact Us

If you have any questions or concerns about this Cookies Policy, please contact us at info@oculina.co.uk.

Please note that this Cookies Policy should be read in conjunction with our Privacy Policy, which provides additional information about how we collect, use, and disclose your personal data.

Last updated: 03/07/2023

CLOSE

Terms and Conditions

Effective Date: 03/07/2023

Please read these Terms and Conditions (“Terms”) carefully before using the website located at www.oculina.co.uk (“Website”). These Terms govern your access to and use of the Website, including any content, features, or services offered.

Acceptance of Terms

By accessing or using the Website, you agree to be bound by these Terms and any additional terms and conditions that may apply to specific sections of the Website. If you do not agree to these Terms, you should not use the Website.

Website Content

  1. The content provided on the Website is for general informational purposes only. We strive to ensure the accuracy and timeliness of the information, but we make no representations or warranties of any kind, express or implied, regarding the completeness, accuracy, reliability, suitability, or availability of the content.
  2. The content on the Website is subject to change without notice. We reserve the right to modify, update, or discontinue any aspect of the Website at any time.

Intellectual Property

  1. All intellectual property rights, including copyrights, trademarks, trade names, logos, and other proprietary information, displayed on the Website are the property of Oculina.co.uk or their respective owners. You agree not to reproduce, distribute, modify, or create derivative works of any such materials without our prior written consent.
  2. You may print or download a single copy of the Website’s content for personal, non-commercial use, provided that you retain all copyright and proprietary notices.

User Conduct

  1. You agree to use the Website in compliance with applicable laws, regulations, and these Terms. You shall not engage in any activity that may interfere with or disrupt the functioning of the Website, its servers, or networks.
  2. You shall not use the Website to transmit or post any content that is unlawful, defamatory, abusive, threatening, obscene, or infringing on the rights of others. You are solely responsible for any content you submit to the Website.

Links to Third-Party Websites

The Website may contain links to third-party websites or resources. These links are provided for your convenience only, and we do not endorse or assume any responsibility for the content, products, or services offered on those websites. You acknowledge and agree that we shall not be liable for any damages or loss arising from your use of any third-party websites.

Limitation of Liability

To the fullest extent permitted by law, we shall not be liable for any direct, indirect, incidental, consequential, or punitive damages arising out of or related to your use of the Website. This limitation of liability applies whether the alleged liability is based on contract, tort, negligence, strict liability, or any other basis.

Indemnification

You agree to indemnify, defend, and hold us harmless from any claims, damages, losses, liabilities, costs, and expenses (including legal fees) arising out of or related to your use of the Website, violation of these Terms, or any breach of applicable laws or regulations.

Termination

We may, in our sole discretion, terminate or suspend your access to the Website, without prior notice and for any reason, including without limitation, breach of these Terms. Upon termination, your right to use the Website will immediately cease.

Governing Law and Jurisdiction

These Terms shall be governed by and construed in accordance with the laws of England and Wales. Any dispute arising out of or relating to these Terms or the use of the Website shall be subject to the exclusive jurisdiction of the courts of England and Wales.

Severability

If any provision of these Terms is found to be invalid, illegal, or unenforceable, the remaining provisions shall continue in full force.

CLOSE

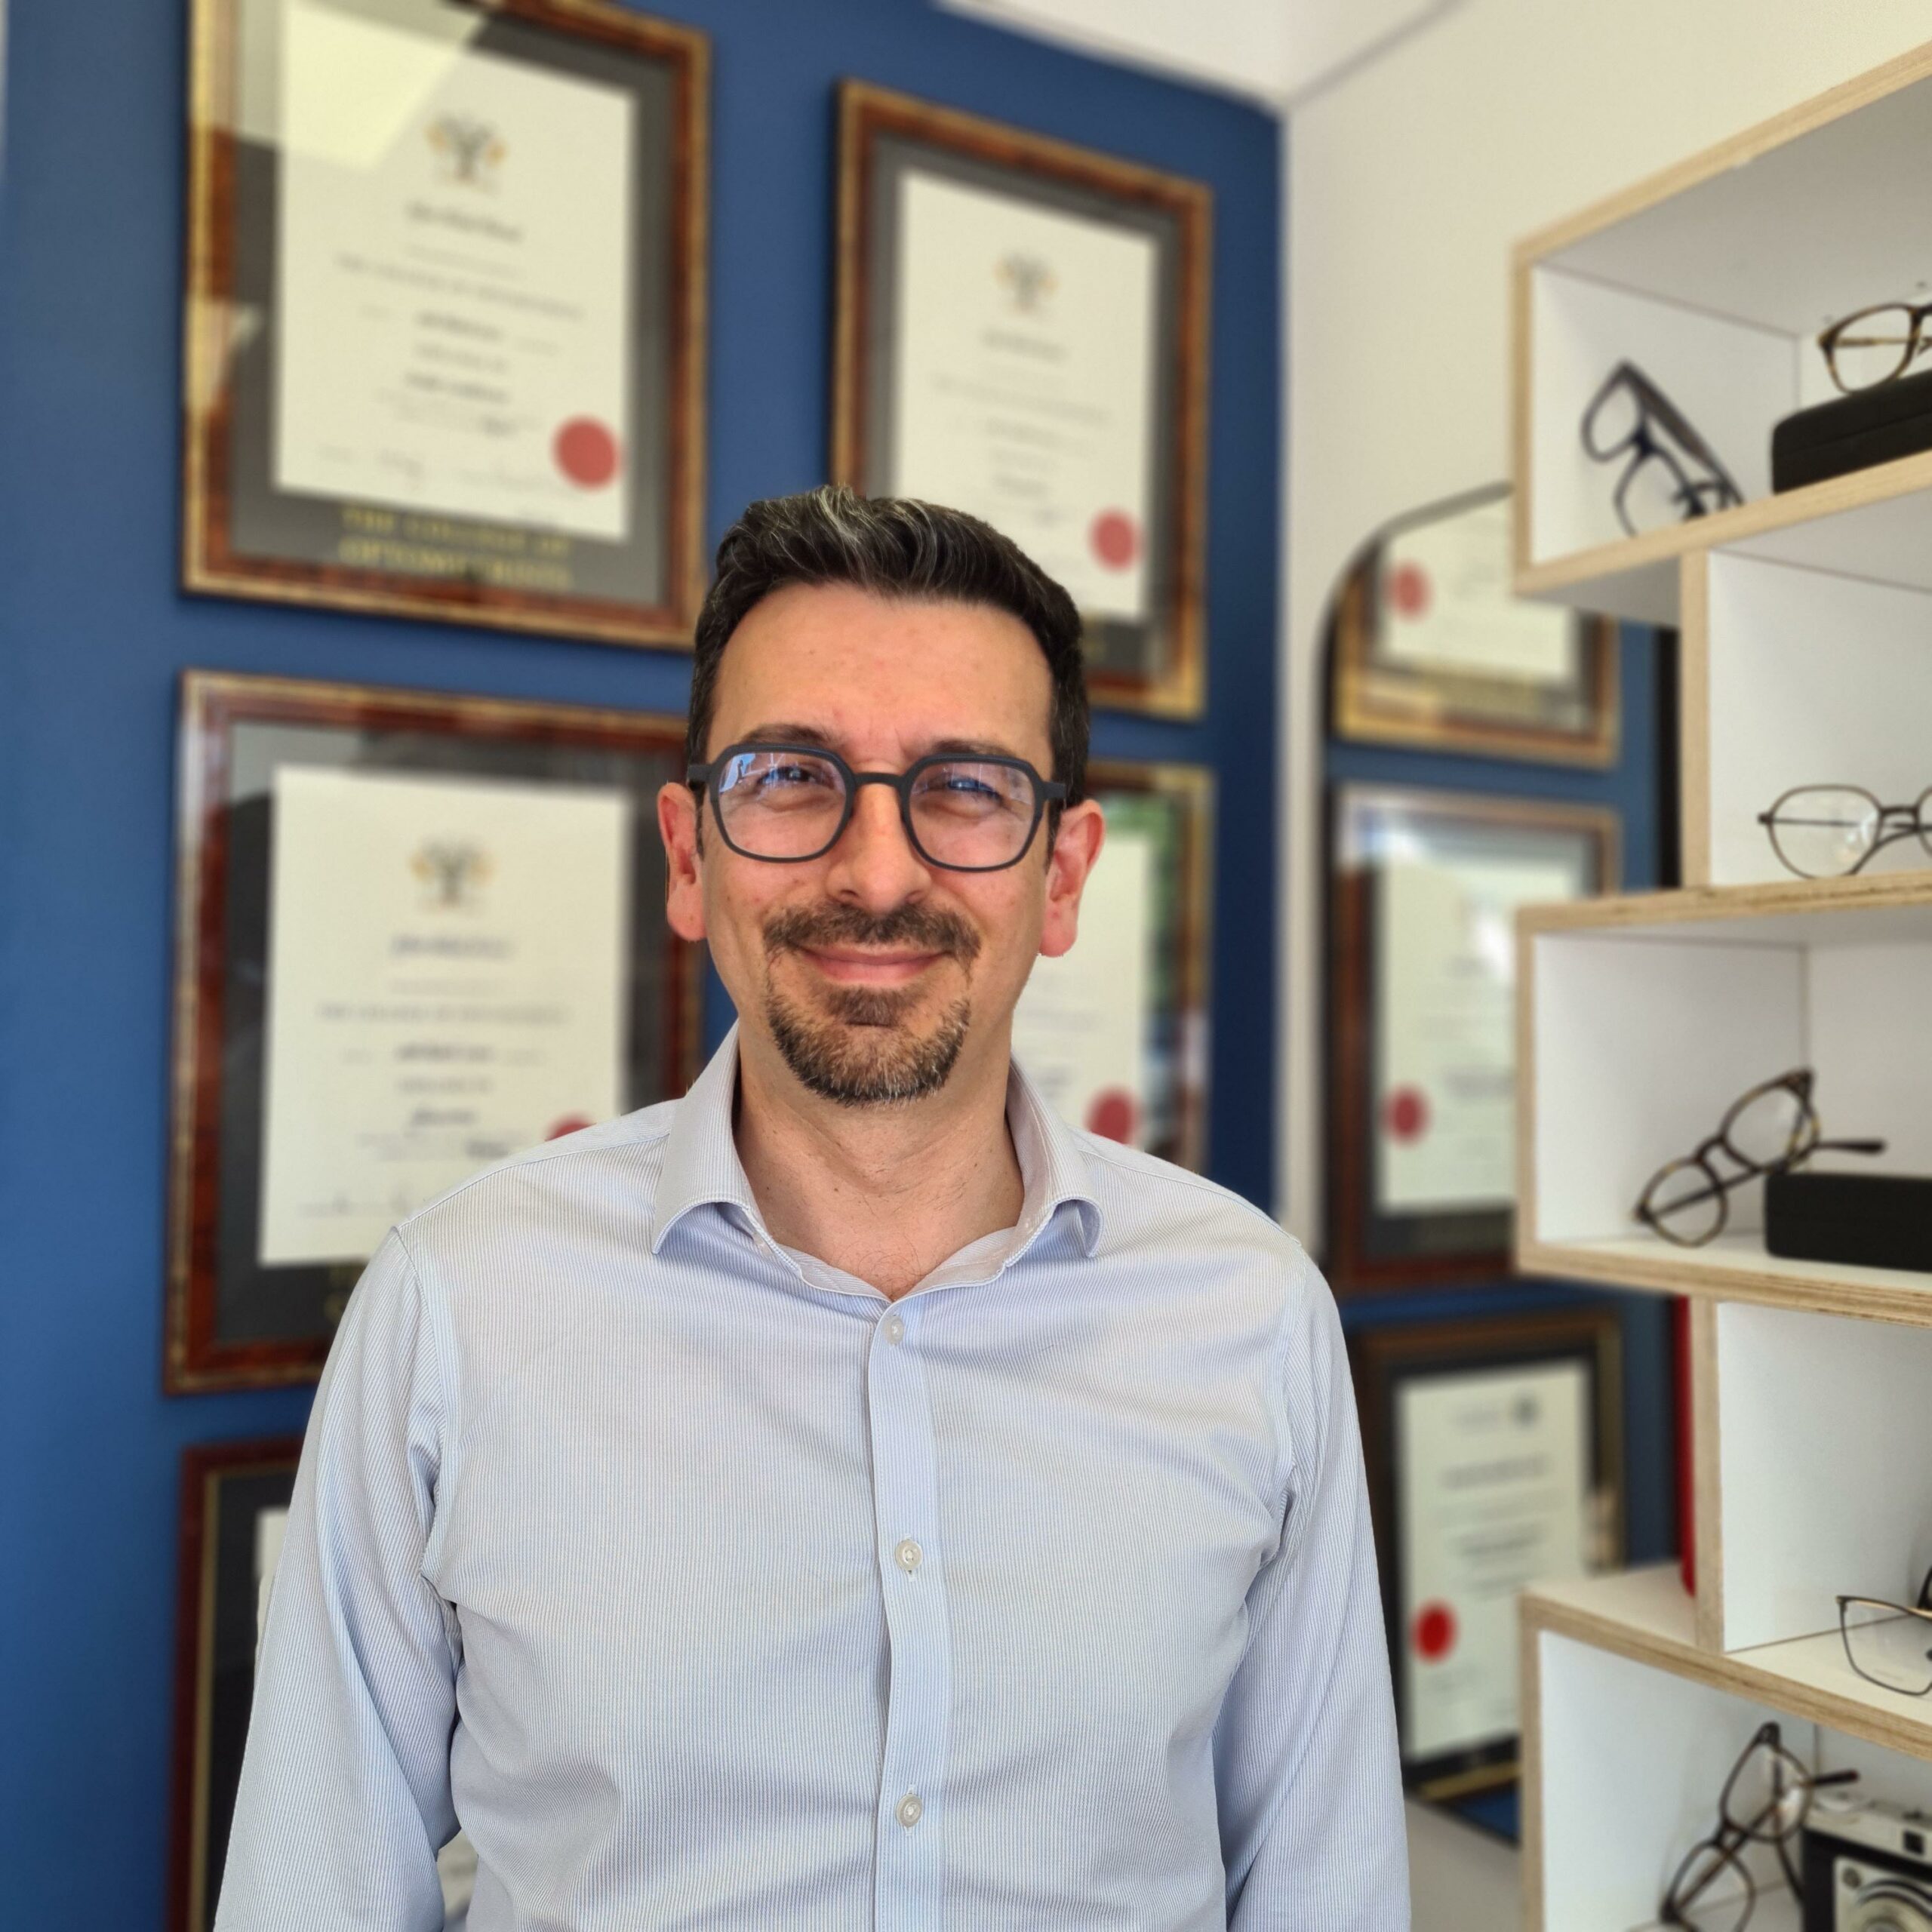
Irfan Ahmed

Specialist Optometrist

FCOptom
DipTpIP, DipGlauc, DipOC, Prof Cert Med Ret

With 25 years of experience in both the community and hospital settings, I have decided to bring that experience to my practice. I have been fortunate enough to attain higher qualifications in Glaucoma, Diabetes, Medical Retina including Macular Degeneration, Independent Prescribing and certification for laser treatments. This journey started in Nottingham QMC, High Wycombe Hospital, where I was head of department for 15 years, Moorfields Eye Hospital, London, and Ashford and St Peters.
In addition to my hospital work, I have worked for most of the multiple and many independent optical practices.

Currently I share my time working within the hospital setting for Glaucoma, and Cataracts, remain an active commitee member for the local optical council and continue my work as a clinical advisor for NHS England, South East.
Oculina aims to provide a high level of eye care, professional advice and guidance, whilst also providing bespoke eye wear focusing on quality over quantity.

My father, who is a renowned Ophthalmologist in Pakistan, has set up a Charitable eye hospital providing eye care for those most in need. I try on an annual basis to help in these eye camps.

And for those who ask, “Oculina” is a combination of Ocular (dedication to the eye) and “ina” intials of my wife and my children (dedication to my family)

So welcome

Arrange a callback

Glad to see you!